Fractional shares….
With the start of a new quarter, comes an update of all three Portfolios as of September 30. Check out the latest holdings and gains for Portfolio 1, Portfolio 2, and Portfolio 3.
After a terrible third quarter, investor sentiment is definitely bearish. However, with very low expectations its possible the fourth quarter could bring a surprise for investors, preferably not a nasty surprise. Heck, after last quarter anything positive would be great!
That being said, I do not have high expectations for this quarter because the US Federal Reserve Bank (Fed) is serious about getting inflation back to its 2% inflation target and they have been very clear about using whatever tools are available in their battle with inflation. As well, I do not expect the Bank of Canada (BoC) to stop hiking interest rates until the Canadian economy starts to feel the pinch of higher interest rates.
On that note, the head of the BoC said, “We have yet to see clear evidence that underlying inflation has come down.” That all but guarantees an aggressive hike in the Canadian interest rate at the BoC’s October 26 meeting. While in the US, the US Labor Department’s employment report showed strong job growth and historic 50-year low unemployment. With high employment numbers and rising wages comes increased spending, which keeps adding fuel to the inflation fire. These numbers essentially force the Fed to maintain aggressive interest rate hikes to get inflation under control.
While we can expect a hike, perhaps in Canada it will not be as big as the last rate hike as Canadian manufacturing activity contracted for the second month in a row. This is a sign those interest rate hikes are starting to dig in as higher borrowing costs, combined with an uncertain economic future, has led to a drop in demand.
As well, the Reserve Bank of Australia (Australia’s central bank) became the first major central bank to slow the pace of interest rate hikes, raising their benchmark interest rate by 0.25% rather than the expected 0.5%.
It will be interesting to see if the BoC announces a smaller interest rate hike or if it will maintain its aggressive 0.75% streak. However, in the US, the higher jobs report almost locks in another aggressive rate hike by the Fed.
In other news this week, the Organization of Petroleum Exporting Countries and their allies, or more commonly known as OPEC+, decided to reduce their collective output by 2 million barrels per day to maintain high oil prices as global demand slows down. It looks like higher gas prices are here for the winter and higher fuel prices are unlikely to dampen inflation. In another sign that rising fuel prices are impacting consumer spending habits, retailer Best Buy (NYSE:BBY) announced that fewer TVs and electronics were purchased this past summer because consumers are having to spend more on gas and groceries.
Subsequent to knocking off US$ 500 billion from the London Stock Exchange, the British government has now seriously damaged its own credibility with investors by reversing course. After making the case that cutting taxes will jumpstart the British economy, and eventually raise greater tax revenues, the British government abandoned their ill-advised plan to drop the top 45% rate of income tax paid on earnings above 150,000 pounds (US$ 167,000) a year, a policy that received near unanimous opposition. Oddly, reducing taxes for the wealthy, while millions of Britons face a cost-of-living crisis, was not popular with the vast majority of British citizens. Who knew? 😊
One thing we do know, the markets started out strong before giving back most of their gains this past week. Now, let’s take a closer look at what happened in the markets and the portfolios this past week….
Weekly Market Review
Monday: The fourth quarter got off to a good start with all four major North American Indexes ending the day up sharply. Analysts and investors are starting to believe the Bank of Canada (BoC) and the US Federal Reserve (Fed) will back off their aggressive interest rate hikes as global financial stability is threatened by the pace and size of the hikes (who am I kidding, they are only concerned about the Fed’s hikes). Investors re-entered the markets to snap up beaten down companies. Oil prices surged as Organization of the Petroleum Exporting Countries (OPEC) considers a sizable reduction in production to maintain prices.
In Canada, gains in energy shares helped Canada’s main stock index, the Toronto Stock Exchange Composite Index (TSX), start the final quarter of the year on a positive note, its biggest one-day gain since April 2020. All eleven Canadian sectors ended higher led by the Energy sector, with the Healthcare sector bringing up the rear.
In the US, the S&P 500 Index (S&P), the Dow Jones Industrial Average (DJIA), and the Nasdaq Composite Index (Nasdaq) had a great day, each up over 2.5%. For the S&P and Nasdaq, it was their best first day of a quarter since 2009. All eleven S&P sectors ended in the black with the Energy sector leading the way and the Consumer Cyclical sector coming in last.
Tuesday: Another big day in the markets with all four Indexes up at least 2.5% as investors feel the central banks (BoC and Fed) will slow their roll when it comes time for the next interest rate hikes. In Canada, the TSX gained more than yesterday which was the highest single day move in two and a half years. Once again, all eleven Canadian sectors ended higher, this time led by the Technology sector which saw Shopify (TSX:SHOP) jump over 12%.
In the US, the S&P and DJIA had their biggest 2-day rally since April 2020. Amongst those leading the charge were the technology generals Microsoft (NASD:MSFT), Alphabet (NASD:GOOGL) and Apple (NASD:AAPL).
Wednesday: Well, that was quick. After a strong two-day rally, the markets came back to earth with all four Indexes ending slightly lower. The question is, are the Indexes taking a breather or is it back to the reality of the downward trend of 2022? The Energy sector was the best performing sector in both Canada and US. Good for oil and gas companies, not so good for us consumers.
In Canada, the gains in the Energy sector were more than offset by losses in nine of the eleven Canadian sectors.
In the US, despite a late afternoon surge all three major American Indexes were unable to dig themselves out of the hole they dug in morning trading, ending the day lower. Despite investor optimism earlier this week, the Fed maintains it will stay the course and continue its aggressive fight against inflation. Despite the gains in the Energy, Technology, and Healthcare sectors, losses in the eight other sectors kept the market’s gains underwater.
Thursday: Another step back for the four major North American Indexes as both the Canadian central bank (the BoC) and the US central bank (the Fed) reiterated they will maintain their respective hawkish stances when it comes to fighting inflation with higher interest rates.
In Canada, the Energy and Basic Materials sectors were the only sectors to advance today. While higher oil prices are good for oil companies, they are not helping the BoC’s battle with inflation. Higher oil prices push the cost of almost everything higher, which fuels inflation.
In the US, the Fed said it expects to raise the US benchmark interest rate by 1.25% by the end of the year. That through a wet blanket on early morning optimism that the Fed would back off their aggressive rate hike pace because of rising jobless claims last week. In the stock market, the higher oil prices propelled the S&P Energy sector higher. Unfortunately, it was the only sector to end in the black.
Friday: The markets want the central banks to ease off on the aggressive interest rate hikes, while the central banks (BoC and Fed) are committed to stay the course. Guess who won. 😊 As a result, the Indexes continued their downward drift for a third straight day. However, the rally at the beginning of the week was enough for each of the four major indexes to post a weekly gain.
In Canada, higher oil prices pushed the Canadian Energy sector to a 15% gain for the week, its largest weekly gain since November 2020. Elsewhere on the TSX, only the Consumer Staples sector was able to end the day in the black, with the other ten sectors all in the red.
In the US, higher job numbers in today’s US Labor Department’s nonfarm payroll report was another nail in the coffin for hopes of a smaller interest rate hike by the Fed. The market sentiment towards another 0.75% interest rate hike plunged all three American into the red this session. However, it was not enough to prevent all three indexes from snapping a three-week losing streak. Analysts and investors now turn to next week’s Consumer Price Index report to see the level of inflation in the US of A.
On the American stock markets, the picture was bleak with all eleven sectors down with the interest rate sensitive Technology sector fairing the worst.
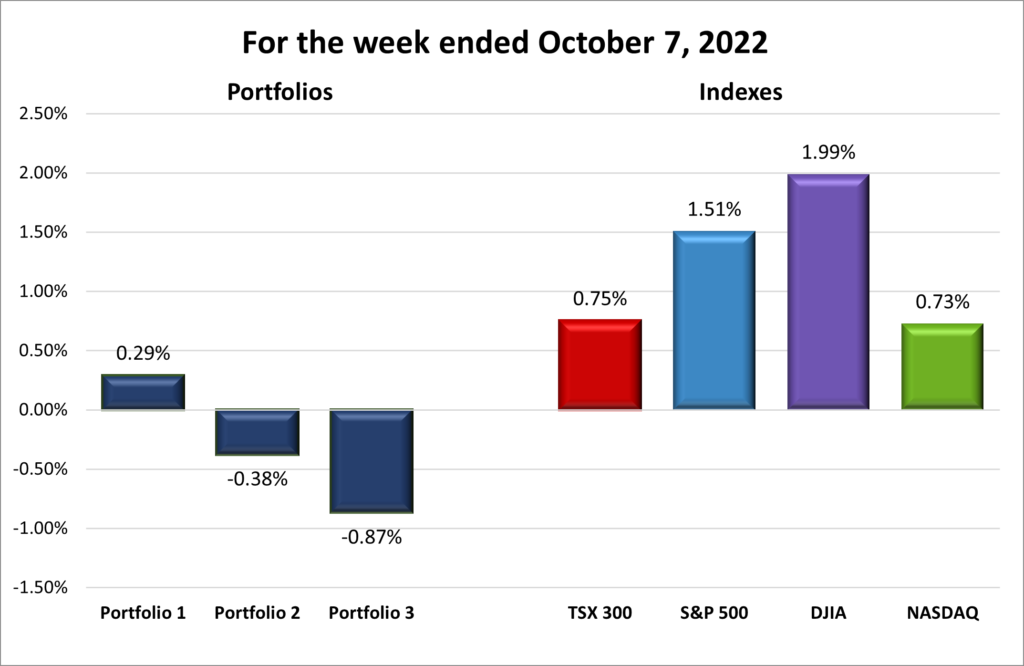
For the week, the TSX gained 0.75%, the S&P 500 added 1.5%, the Dow advanced 1.99% and the Nasdaq rose 0.73%.
Weekly Portfolio Review
What a strange week it was in the North American stock markets. The week started off with strong upward movement thanks to investor optimism that the Fed would be less aggressive with their next interest rate hike. When the Fed reiterated their commitment to aggressive action in their battle to reign in inflation on Wednesday, the markets gradually retreated for the rest of the week (as you can see in the above chart). Fortunately, the great start was enough for all four Indexes to overcome the late week slide and end the week in the black.
In the chart below, you can see the DJIA, with it is 40 large, mature companies, performed better than the S&P and Nasdaq with their interest sensitive, growth-oriented companies, and the more commodity weighted TSX.
As for the Portfolios, considering all four Indexes ended the week higher, I was a bit surprised that only Portfolio 1 ended higher. As of Thursday, all three were well into the positive but Friday’s sharp declines pushed them down considerably. After looking at Portfolio 2’s ‘market movers’ on the TD Direct Trading platform, MongoDB (NASD:MDB) sank almost 5%, Microsoft slipped over 5% and Guardant Health dropped almost 7%. As for Portfolio 3, along with Microsoft’s fall, Shopify and Cloudflare (NYSE:NET) each plunged more than 9%. Declines like that would do it. Sigh!
Companies on the Radar
For avid sports car buffs, Volkswagen’s Porsche went public September 29 on the Frankfurt Stock Exchange under the trading symbol “P911,” a tribute to their iconic sports car. One week later, Porsche surpassed parent company Volkswagen as the most valuable car maker in Europe. Porsche was worth US$ 81.2 billion, compared to VW’s US$ 76.7 billion.
No word if/when Porsche shares will be available in North America. With Porsche only trading on the Frankfurt Exchange it would be hard/expensive to become an owner of Porsche. Plus, while Porsche makes fine cars, I would be happy to have one, Porsche does not have the same appeal for me as Ferrari. 😊
Otherwise, with the markets continuing their downward spiral, I am going to sit on the sidelines for now. However, I’m still keeping an eye on Amazon (NASD:AMZN) and Ferrari (NYSE:RACE). Taking advantage of low share prices for long term gain is the first half of buy low, sell high, and is rarely a bad thing. 😊
Portfolio Update
Portfolio 1
Portfolio 1 for the week ended October 7, 2022: UP 
- Lightspeed Commerce (TSX:LSPD) added a new piece to their Lightspeed Restaurant product. Lightspeed Advanced Insights. The add on module provides instantaneous analysis on every transaction and identifies developing trends that may help improve the business.
- Despite record deliveries for the third quarter, Tesla (NASD:TSLA) missed expectations due to problems delivering the electric vehicles to buyers. This puts them in a hard spot to meet their own stated goal of growing deliveries by 50% annually.
This will help. Tesla is set to deliver 100 of their Semi trucks to PepsiCo (NASD:PEP) on December 1. PepsiCo will be the first company to start using Tesla Semi trucks as they attempt to lower their gas emissions. - Rivian Automotive (NASD:RIVN) said it produced 7,363 units in the third quarter, 67% more than the preceding quarter, and maintained its full-year target of 25,000. Hopefully, Rivian has its supply chain issues worked out and ramp up productions and deliveries.
- The European Union (EU) voted to make USB-C connectors the standard for most devices sold in the EU. Companies have until the end of 2024 to comply. Despite what Apple may think, this is good news as consumers will not have to buy different chargers every time they switch vendors.
Activity
No significant activity to report this week.
Dividends
Dividends Received this week for the following companies:
Companies followed by DRIP (Dividend Re-Investment Plan) indicate additional shares were purchased with the dividend. Any cash leftover was added to the cash balance.
Canadian $
Cargojet Inc (TSX:CJT)
Telus Corp (TSX:T)
US $
No US$ dividends this past week.
Quarterly Reports
No quarterly reports this past week.
Portfolio 2
Portfolio 2 for the week ended October 7, 2022: DOWN 
- The Banker Magazine named Scotiabank (TSX:BNS) Investment Bank of the Year for the Americas region. The award is for providing excellence to their Global Banking and Markets clients. This award joins other awards won by Scotiabank in 2022, including three wins in the 2022 Euromoney Awards for Excellence and six wins in the 2022 Global Finance Sustainable Finance Awards.
- Disney’s (NYSE:DIS) ESPN unit is on the verge of entering a partnership with DraftKings (NASD:DKNG), a leader in online sports netting. The partnership will allow ESPN to take advantage of the growing sports betting industry.
Activity
No significant activity to report this week.
Dividends
Dividends Received this week for the following companies:
Companies followed by DRIP (Dividend Re-Investment Plan) indicate additional shares were purchased with the dividend. Any cash leftover was added to the cash balance.
Canadian $
Canadian Natural Resources Ltd (TSX:CNQ)
Telus Corp (TSX:T) DRIP
US $
No US$ dividends this past week.
Quarterly Reports
No quarterly reports this past week.
Portfolio 3
Portfolio 3 for the week ended October 7, 2022: DOWN
- Cloudflare (NYSE:NET) announced a plan to make physical security keys more accessible and economical for customers to improve the security of their business and their employees. Security keys are the most secure form of phishing-resistant multi-factor authentication and Cloudflare will make Yubico security keys available at a reasonable price to Cloudflare customers.
- Brookfield Asset Management (TSX:BAM.A) is putting up US$ 1.7 billion to get into the music industry. Brookfield is taking a sizable minority interest in Primary Wave Music to invest in music copyrights. The infusion of cash will be used to acquire music rights from top artists.
- Following talks with the European Commission that some of Shopify’s merchants engaged in fraudulent practises, such as fake offers and counterfeit products, Shopify plans to implement stronger consumer protection measures.
Activity
Sold Acuity Ads (TSX:AT) Similar to last week’s sale of Acuity in Portfolio 1, I bought these shares around C$ 2.50, should have sold a long time ago but kept believing in their new Illumin product. After a few disappointing quarters where sales have not been as high as expected, I have lost faith in management and their much-hyped Illumin product.
Dividends
Dividends Received this week for the following companies:
Companies followed by DRIP (Dividend Re-Investment Plan) indicate additional shares were purchased with the dividend. Any cash leftover was added to the cash balance.
Canadian $
TD U.S. Equity Index ETF (TSX:TPU)
Brookfield Asset Management Inc (TSX:BAM.A)
US $
No US$ dividends this past week.
Quarterly Reports
No quarterly reports this past week.